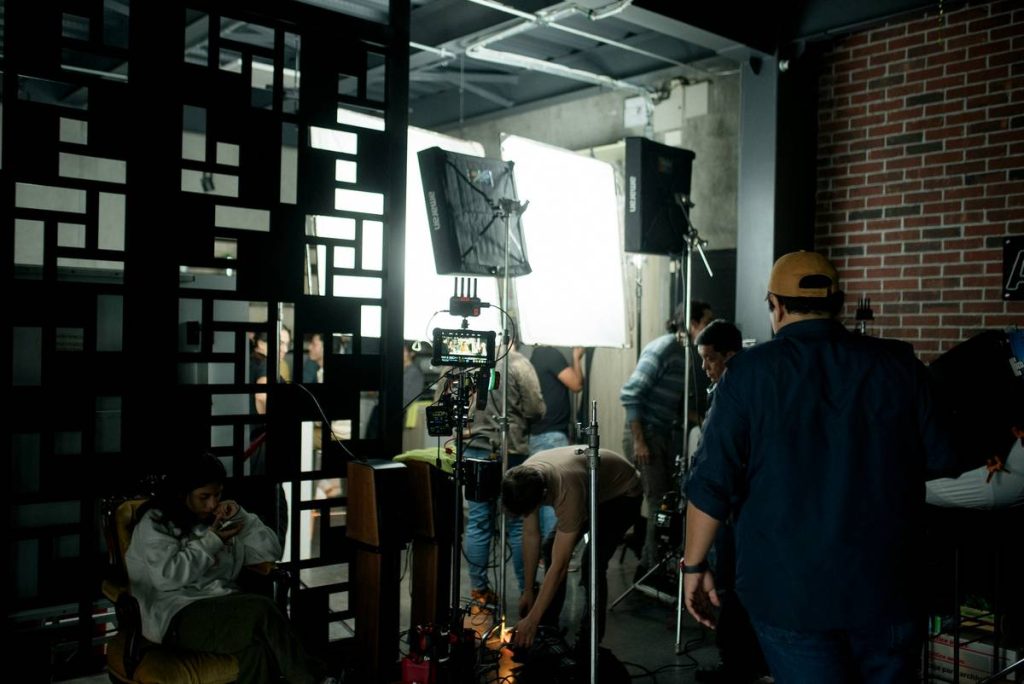
Picture this: you’re shooting a crucial outdoor scene for your indie film, and suddenly, a flash mob of curious onlookers swarms the set. Equipment gets jostled, an actor trips over a cable, and your assistant director suffers minor injuries trying to clear the area. Without proper coverage, that “minor incident” could cost you thousands—or even shut down production. If you’re working in film, especially on location, crowd control insurance isn’t optional—it’s essential risk management disguised as paperwork.
In this guide, we’ll break down why this niche coverage matters for your budget, how to secure it without overspending, and real lessons from filmmakers who skipped it (and paid dearly). From choosing the right policy to avoiding industry traps, these seven actionable tips will keep your shoot—and your finances—on track.
Table of Contents
- Why Crowd Control Insurance Matters
- Step-by-Step Guide to Getting Covered
- Best Practices for Smart Coverage
- Real-World Case Studies
- Frequently Asked Questions
Key Takeaways
- Crowd control insurance covers liability for injuries or property damage involving unauthorized or unmanaged spectators during film shoots.
- Standard general liability policies often exclude crowd-related incidents unless explicitly endorsed.
- You can typically add this coverage as an endorsement to your production insurance package for a modest premium increase.
- Failing to secure it can lead to out-of-pocket expenses exceeding $10,000 per incident, according to industry claims data.
- Always verify crowd size estimates with local authorities—underreporting inflates your risk exposure.
Why Crowd Control Insurance Matters
In personal finance, few things erode budgets faster than unexpected liabilities. For filmmakers, crowd-related incidents are among the most common yet overlooked risks. Standard production insurance includes general liability, but many policies exclude “uncontrolled public gatherings”—meaning if someone wanders onto your set and gets hurt, you’re personally liable.
I learned this the hard way during a low-budget music video shoot in downtown Austin. We didn’t expect foot traffic, but a nearby festival drew hundreds. A pedestrian slipped on a dolly track, sprained their ankle, and sued. Our insurer denied the claim, citing lack of crowd management planning. We ended up paying $8,500 out of pocket—a devastating hit for a $40k production.

Step-by-Step Guide to Getting Covered
1. Assess Your Shoot’s Public Exposure
Ask: Will you be filming in public spaces? Near sidewalks, parks, or event zones? If yes, you likely need this coverage.
2. Talk to Your Production Insurer Early
Don’t wait until location scouting ends. Reach out during pre-production. Most specialty insurers like Film NYC offer customizable endorsements, including specific crowd control insurance riders.
3. Document Your Crowd Management Plan
Insurers often require proof of perimeter barriers, security personnel, or signage. Even a simple plan boosts approval chances and lowers premiums.
4. Confirm Coverage Limits
Aim for at least $1–2 million in liability coverage. According to the Insurance Journal, average third-party injury claims in entertainment exceed $15,000.
Best Practices for Smart Coverage
- Bundle wisely: Add crowd control insurance to your existing production package—it’s cheaper than a standalone policy.
- Verify municipal requirements: Some cities (like Los Angeles) mandate minimum liability limits for public shoots—check local ordinances.
- Never rely on “it won’t happen to me” thinking: Over 60% of indie productions face unplanned bystander encounters, per Film Independent surveys.
- Avoid this terrible tip: “Just use your personal auto or home insurance.” Those policies universally exclude commercial film activities—and void your claim instantly.
Real-World Case Studies
In 2023, a documentary crew filming a protest scene in Chicago failed to secure crowd control insurance. When tensions escalated and a protester was injured by falling gear, the production company faced a $22,000 settlement. Their general liability insurer denied coverage due to “failure to mitigate public risk.”
Conversely, a Brooklyn-based short film team budgeted $300 for a crowd endorsement through their insurer. When a tourist wandered into a rig and damaged $5k in lighting equipment, the claim was processed within 10 days—zero out-of-pocket cost.
Frequently Asked Questions
Is crowd control insurance the same as general liability?
No. General liability covers broad third-party claims, but often excludes incidents involving unmanaged crowds unless specifically endorsed.
How much does crowd control insurance cost?
Typically $150–$500 as an add-on to a production policy, depending on shoot scale, location, and duration.
Do I need it for closed sets?
If your set is fully controlled (e.g., soundstage with locked doors), probably not. But any public adjacency increases risk.
Can credit cards provide this coverage?
No. While some premium cards offer travel or rental insurance, they don’t cover commercial production liabilities.
Mistakes in film insurance aren’t just plot holes—they’re budget holes. Don’t let one unsecured bystander derail your project. Ready to lock down your coverage? Contact us today for personalized guidance. And for more on our standards, visit our About Us page—we’ve helped creators navigate complex policies since day one. (By the way, we take data privacy seriously; review our Privacy Policy anytime.)
Final thought: Great films manage chaos—but smart producers insure against it.